Dan Cummins Chevrolet Buick of Paris

Address

1020 Martin Luther King Junior Boulevard, Paris, KY 40361, USA

Sales Hours

Monday - Friday: 8:30 AM - 8:00PM
Saturday: 8:30 AM - 6:00PM
Sunday: Closed

Service Hours

Monday - Friday: 7:30 AM - 6:00 PM
Saturday: 8:00 AM - 3:00PM
Sunday: Closed

Phone

Sales: (877) 392-5449

Service: (877) 750-3289

Dan Cummins Ford Lincoln

Address

4080 Lexington Road, Nicholasville, KY 40356, USA

Sales Hours

Monday - Friday: 8:30 AM - 8:00PM
Saturday: 8:30 AM - 6:00PM
Sunday: Closed

Service Hours

Monday - Friday: 7:00 AM - 6:00PM
Saturday: 8:00 AM - 3:00PM
Sunday: Closed

Phone

Sales: (859) 349-1227

Service: (859) 657-8184

Dan Cummins Chrysler Dodge Jeep RAM of Paris

Address

2021 Alverson Drive, Paris, KY 40361, USA

Sales Hours

Monday - Friday: 8:30 AM - 8:00PM
Saturday: 8:30 AM - 6:00PM
Sunday: Closed

Service Hours

Monday - Friday: 7:30 AM - 6:00PM
Saturday: 8:00 AM - 2:00PM
Sunday: Closed

Phone

Sales: (859) 587-3835

Service: (859) 587-3836

Dan Cummins Chevrolet Buick of Georgetown

Address

1470 Cherry Blossom Way, Georgetown, KY 40324, USA

Sales Hours

Monday - Friday: 8:30 AM - 8:00PM
Saturday: 8:30 AM - 6:00PM
Sunday: Closed

Service Hours

Monday - Friday: 7:30 AM - 6:00PM
Saturday: 8:00 AM - 3:00PM
Sunday: Closed

Phone

Sales: (502) 542-6488

Service: (502) 542-6561

Dan Cummins Chrysler Dodge Jeep RAM of Georgetown

Address

215 Connector Road Georgetown, KY 40324, USA

Sales Hours

Monday - Friday: 8:30 AM - 8:00PM
Saturday: 8:30 AM - 6:00PM
Sunday: Closed

Service Hours

Monday - Friday: 7:30 AM - 6:00PM
Saturday: 8:00 AM - 3:00PM
Sunday: Closed

Phone

Sales: (502) 287-1506

Service: (502) 908-9149

Blog / Kentucky Auto Financing

The Rarest Chevy Trucks You Wished You Owned

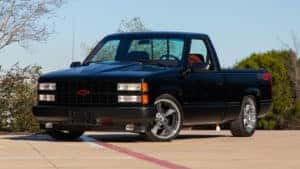
1993 Chevy 454 SS
So you're looking for a used truck, and you've ultimately concluded that you want an older Chevy. Where do you start? Well the possibilities are almost endless (with the keyword being endless). While your local Chevy dealerships in Lexington, KY likely has a variety of different Chevy trucks, there are a handful that they're likely missing. These are the rarest Chevy trucks you're not likely to find on any dealership lot, and would be lucky to even spot out in the wild. 

Learn about Rocky Ridge Trucks

1990-1993 Chevy 454 SS

The truck was based off the Chevy 1500, except the 454 SS featured the 454-cid V-8 engine, capable of producing 230 horsepower and 385 pounds of torque. So basically, they took a small truck and put in a heavy, powerful engine. Despite the improved motor, the car's acceleration trailed the Camaro Z/28 and Ford Mustang GT, compiling a 15-second quarter-mile time. The car was eventually pushed out by the Sport model of the Chevy 1500. So if you ever happen to come across an early-90s Chevy truck, how can you identify whether it's a 454 SS? They're pretty recognizable from the red interior and soft garnet red cloth seats.

1958 Chevy Cameo

1958 Chevy Cameo Only 1,405 of the 1958 trucks were built, the last of the popular Cameo line. The vehicle features several exterior updates, like the inclusion of sheet metal, quad headlamps, improved grill/hood emblems, and a variety of new colors to choose from. The truck didn't end up being very popular, but it paved the road for similar future trucks, including the Ford Styleside, Dodge Sweptside, and the Chevy Fleetside. The truck is easily identifiable by it's sedan-like features and vast bed.

Chevrolet S-10 EV

Chevrolet S-10 EV Only 492 of these trucks were actually produced, and Jalopnik.com claims that only 60 of them were ever sold! What made the truck so unpopular? The car was electrically powered via the EV-1 engine, allowing for only 114 horsepower. The car differed from previous S-10s in that it was configured with front-wheel-drive, as opposed to the standard rear-wheel-drive setup. The car accelerated from 0 to 50 mph in 13.5 seconds, and it's top speed peaked at 70 mph. It was only on the market from 1997 through 1998 before it was discontinued.
Posted in:

Related Posts

car payment, payment calculator

Will a Car Payment Affect my Credit?

You've been thinking about a car payment lately - especially since you spotted that new Chevy Silverado on the lot. Eyeing its new wheels, big grille and spacious truck bed you start to wonder something. "Will a car payment affect my credit?" We hear you. If you want to know if your car payment can affect your credit, read on. You can get a free credit report every 12 months. Your Credit Report Before we get into the meat of this article, lets first focus on the potatoes: where to find your credit report. There are four companies that have information on your credit score. They are Experian, Equifax, TransUnion and Credit Karma. You can get a free credit report from them every 12 months to ensure your credit score is being reported correctly. There are two important things to look at when viewing your credit score: Account types and current status. Account Types: This where all your accounts that factor into your credit score are listed. Car payments, like college loan and mortgage payments, are listed as installment accounts. This means that you're paying a set amount each month for a set number of payments. Current Status: This is the status of each account. If you don't miss payments at all and pay on time, your account should be listed as "current" or "paid as agreed." It's ALWAYS a good idea to pay on time. To avoid high payments, check out this post on car payments and the Dan Cummins payment calculator to see what you can afford. If your credit is checked several times in under 30 days, all credit checks within that time are counted as one. So, What Does Affect Credit? "Alright," you might be thinking. "What does affect credit?" There are two things that affect your credit score. One is car loan shopping. Every time you shop for a car and its loan your credit does take a hit. But there is a little trick you can use to minimize this hit. Suppose you need a new truck. You've recently bought a spot at an antique shop and need something to haul your inventory. Before you rush off to test drive trucks, research what one you want. Then, once you have a pretty good idea of the make, model, and price, keep your car shopping short. Finance your new truck within 30 days. Why? It has to do with credit checks. Each time you get a loan (car or otherwise) your credit score is checked. The more checks there are, the more they negatively affect your credit score. However, if your credit is checked several times in under 30 days, all credit checks within that time will be counted as one. So instead of it looking like your credit is being pulled several times, it will look like your credit score is being pulled only once. "What if I need two buy two cars?" Life happens. Just when you've settled on your new car, your partner's car breaks on you.  Just be sure to complete their car purchase within the 30-day window and you should be fine. So what's the other thing that affects your credit score? Keeping up with your car payments. Making consistent car payments does improve credit. Yes, Financing Your Truck Can Help While it's true getting your credit checked for a car loan negatively affects your score, payments offset that. How? Let's say you decided to finance that 2019 Chevrolet Silverado. It has everything you need and couldn't be happier. Each time you make a car payment on time your credit score improves. That's because the payments show you're reliable and are making enough income to cover the payments. In fact, having a car payment can improve your score so much it can help you with other loans. Imagine this a moment. You've been living in an apartment and want to upgrade to home ownership. You look at your savings/bank accounts and get a pre-approval for a loan. Then, after finding your perfect starter home, you begin applying for a home loan in earnest. As the lender looks over your accounts and information they'll also see your credit score. And because you've been making steady, on-time car payments your credit score is pretty decent. This makes lenders more willing to give you an affordable interest rate. "But how can I make sure my car payments are affordable?" Check Out Our Payment Calculator Credit score improvement hinges on the fact that you're making payments on time. So what can you do to make your car payments are easy to make? Use Dan Cummins Payment calculator. With this simple tool, and some quick information from you, you can find out exactly how much you can afford each month. That way, you can plan your budget so your payment is easy to make without fail. Contact Dan Cummins to See What Your Car Payment is Today! See how you can improve your credit with Dan Cummins car payment calculator. To find out which car meets your requirements, talk to our friendly staff. Leave a message or call us at 877-661-2805. Click here to apply for auto financing and get pre-approved in seconds. Will a Car Payment Affect my Credit? | Dan Cummins Auto Group – Louisville, KY
$0 down

How to Get $0 Down When Buying a Car

You want to buy a car and you really need to buy with $0 down payment. What are your options? Owning a car is a necessity. Whether for daily commute to work or dropping kids to school or running errands, it is one thing you can count on needing in your daily life.  Well, unless you have the cash to buy a vehicle straight out, then you'll need to obtain a loan.  When cash is not available, how do you buy without a down payment? Read on to know how to buy a car without a down payment. $0 Down Payment There could be many reasons for you to opt for buying a car with zero down payment. You might be hesitating because you are not sure if you can buy a car with bad credit. Otherwise, you might not be able to afford it at the moment, but you seriously need it. Hence, it leaves you in a dilemma. As a matter of fact, putting no money down to buy a car is possible. But first, you need to consider a few important things. The most important thing to review is whether this is the right car to buy at that moment. Try to find alternative options. Consider Buying Used Cars Vehicles cost more when brand new.  If your income doesn't support servicing a new vehicle loan for the full amount, then you'll be required to make a down payment to ensure that the payment fits your budget.  The bank has to be sure that you can afford the car.  If it's not possible to come up with a down payment to get the loan amount to an affordable level, you may opt to find a lower priced car to match your budget.  Enter the used car. Used vehicles are less expensive and may make a better fit for your budget.  The loan amount is lower and thus you have a better chance for the bank to give you a auto loan approval with zero down. “The best way to determine if you like a car is to go on a test drive.” Trade In Your Old Car Another way to not have to come up with cash for a down payment is to trade in your old car. Banks will see this in the same way as a down payment if your car has equity.  Equity in a car means that it is worth more than what you owe on it.  If you have a "free and clear" trade, then that means there is no loan balance and thus it's the best scenario to be in. Trading in the car with equity will reduce the loan amount in the same way as a down payment and thus make the loan more affordable to you.  In some states like Kentucky, this will reduce your sales tax on the car deal as well. Know Your Credit Report Firstly, assess your current financial situation. Your financial situation is what your lender considers when approving your loan. In particular, your credit report and credit score become deciding factors in whether or not the loan is approved or if you need a down payment. Some auto lenders won’t let you buy a car with bad credit rating.  Or if you are approved, they may ask you to make a considerable down payment on the loan.  This shows commitment to the vehicle and in their eyes makes it less likely that you will let the vehicle get repoed. Conversely, good credit might get you a zero down loan with a nice low rate.  This will be especially helpful to you as the average monthly payment for a car in the US is $499.  The lower the rate the lower the payment. For instance, let us say that you have a good credit score, 680 and higher. This could even persuade the lender to charge low interest rates, with $0 down payment. Hence, know your credit report and try to improve your score. Paying all your bills in a timely manner and having a steady income help raise your score. Share the Responsibility As a final option, you could get a friend or family member to cosign.  A co-signer's credit score when stronger than yours, can get a loan officer to give you approval.  This is such because the co-signer adds income and additional stability to the loan application. When a person co-signs on a loan with you, they have the responsibility to make sure the loan payments are made, just like you do.  Late payments will hurt both parties credit scores and timely payments will help build up the credit. A co-signer also may be on the title to the vehicle and have rights to ownership of the car. “Adding a cosigner improves your loan terms.” Get a Low Interest Rate Newer cars have the lowest interest rate.  If you start shopping for too old of a vehicle, then the bank may reduce the loan term and raise the rate.  This is because older cars come with problems and when a car breaks sometimes people don't have the money to make the repairs.  Then they don't make the payments.  You can look for other options also, like trading in your existing, well maintained car. Instead of opting for a top-of-the-line car, choose a car that fits your budget. Furthermore, try to improve your credit report. Contact Dan Cummins and Buy Your Dream Car with a $0 Down Payment Today! Finding the right $0 down offer is easy with Dan Cummins. To find out which car meets your requirements, talk to our friendly staff. Leave a message or call us at 877-661-2805. Click here to apply for auto financing and get pre-approved in seconds. How to Get $0 Down When Buying a Car | Dan Cummins Chevrolet & Buick – Louisville, KY

Payment calculator, car payment

What Will My Car Payment Be?

A new car payment. It's not something you anticipated for the new year, but then your go-to car finally died. As you start to daydream about all the new cars you want to test-drive, a thought pops in your head: "What will my new car payment be?" If you want to know what your possible new payment might be, read on. Car payments are based on many factors, like interest rate and loan terms. What Goes Into My Car Payment? Before we get into what you could pay and where to calculate that, lets first go into the makeup of a car payment. As you might already know from previous cars, a typical payment is based on: Vehicle price Interest rate Loan term Down payment Trade-in value While all of this helps determine what you might pay each month, there are a few things to consider. It's not impossible to buy a car with bad credit. The first is your credit score. Unfortunately, the lower your credit score is the higher your interest rate will be.  That's why it's important to research your credit score to avoid buying a car on bad credit. We're not saying it's impossible or that you can't buy a car with bad credit. At Dan Cummins we have many specialists to help you. But if you want a high-end model with all the extras, it's best to know your credit score. Think Beyond Monthly Payment Another factor that affects your car payment is the loan term. This means the loan's duration. The longer your loan is, the smaller your monthly payment will be. This might seem like a great idea at first, but longer loan payments don't mean you're paying less. In fact, when you factor in interest, you could be paying more. For instance, let's say you're looking at a 2019 Chevrolet Malibu. The starting price is around 20K. Your interest rate is about 4.9% and you're putting $0 down. To keep the payments low you opt for a loan that's 84 months.  The car payment, interest and all, is $282 a month. Sounds great, right? Of course, it does! But by the end of the loan, your interest could total about $3,688. However, if you opt for a shorter loan term, say, 36 months, the total interest you pay drops to about $1,564. That's well under half of the first amount. "But wouldn't that make my car payments jump up?" Yes, it would, but the complete amount you pay for the Malibu would be less overall. Use services like Kelly Blue Book and Consumer Reports to see what others have paid. Ways to Lower Payments If you have your mind set on lower payments (we don't blame you), here are a few things you can do. First, try to put down as much as you can. The general rule of thumb is about 20% of the car's worth. If we went with the Malibu from before, the down payment would be about $5,000. "What if I have less than that?" Good question! While 20% is ideal, it's fine to come in with less than that. As long as your putting down something your car payments will be less than if you put down nothing. Second, see what others have paid for the model you want. How? By using Consumer Reports Car Buying Service. All you do is plug in the car you want, your zip code, and it will tell you what others in your area have paid. See what you could pay with Dan Cummins car payment calculator. You can also do the same with Kelly Blue Book. The bonus of using Kelly Blue Book is that you can customize your search beyond make and model. That way, you can see what others have paid for the exact model you want that has the exact extras you want. "Okay, this is great and all, but how can I really see what my monthly car payment could be? " We hear you. If you want to get a clear look at what your car payment might be, check out Dan Cummins Car Payment Calculator. All you have to do is plug in some information such as car price, interest rate, loan term, and down payment or trade-in. Press the calculate button and you'll get a pretty good idea of your car payment. Contact Dan Cummins to See What Your Car Payment is Today! See how you can afford your dream car with Dan Cummins. To find out which car meets your requirements, talk to our friendly staff. Leave a message or call us at 877-661-2805. Click here to apply for auto financing and get pre-approved in seconds. What Will My Car Payment Be? | Dan Cummins Auto Group – Louisville, KY